Land, equipment,
operating lines.
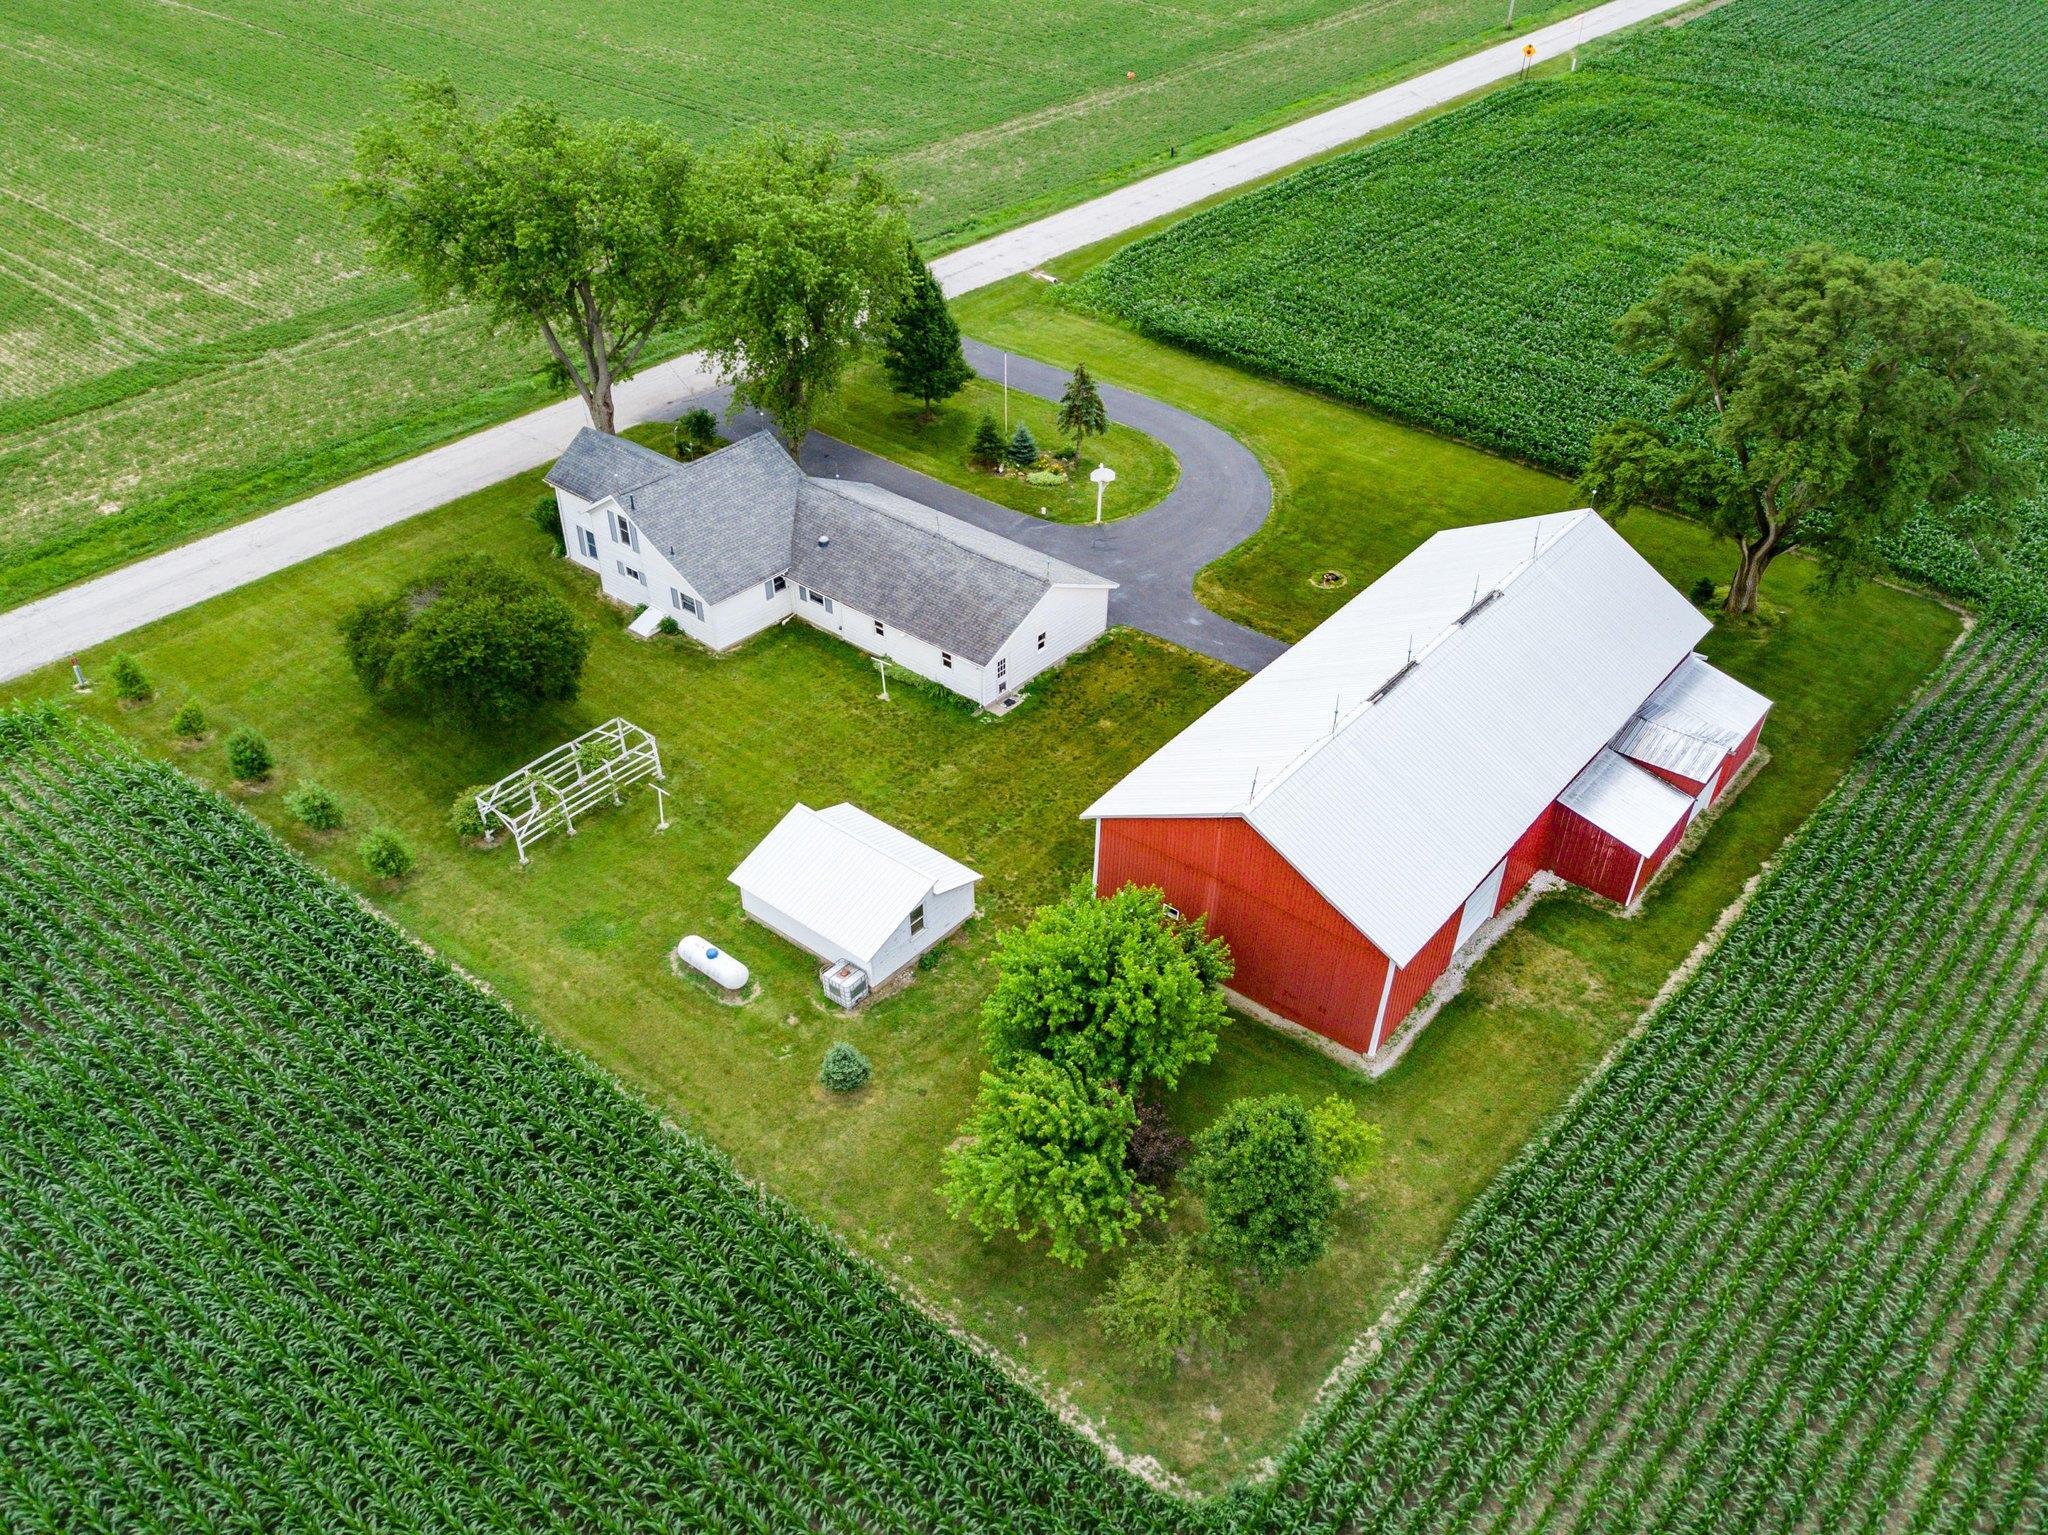
Financing built for the way farm operations actually run: seasonal cash flow, land purchases, and equipment that can't wait for a slow approval.
- ✓ Terms up to 30 years
- ✓ Fixed and Variable Rate Options
- ✓ Fast Loan Decisions
Farmland mortgage
Buy, refinance, or expand your land base with a fixed or adjustable rate sized to a row crop or livestock operation.
Operating line
Cover seed, inputs, and labor before harvest pays you back. Draw what you need, when you need it.
Equipment financing
Finance tractors, combines, and other equipment on terms that fit your operation's cash flow.
Affordable rates. Flexible terms.
What to expect

Reach out directly
Have questions? Connect with the team below.


Frequently Asked Questions
What types of farm loans do you offer?
We offer two core lending products. Farm mortgages for purchases, refinances, and expansion, with amortizations available up to 30 years. We also offer traditional operating lines to cover your seasonal needs. Contact us to hear more about what we can offer.
How much down payment is needed for a purchase?
For traditional real estate secured mortgages, financing is generally available up to 70% loan to value (LTV), which means a 30% down payment is required. The final loan amount depends on credit approval and the approved appraisal. In some cases, our financial partners may provide higher financing options. Contact us to learn what you may qualify for.
Are there any prepayment penalties if I pay off my loan early?
No prepayment penalties. You can pay off or refinance whenever it makes sense for your operation. One exception: some products require paying interest through your scheduled payment date if you pay off early. Ask us about the details for your loan type.
What interest rate and terms can I expect, and is it fixed or variable?
Loan rates and terms vary based on loan type, loan amount, credit profile, and farm financials. We offer competitive fixed and variable rate options. Contact us to get your quote.
How long does it take to close?
Once we have your underwriting documents, three years of tax returns, a current balance sheet, and a completed application, we can usually turn around a decision quickly. Closing then depends on third parties like appraisers and title companies, which can take a few weeks. Reach out early to get the process started; we'll work to move things along wherever we can.